Six months sounds like a lot of time right up until about month four, when it starts sounding like no time at all.
If you are roughly sixty days out from your first student loan payment, you are in the useful window. Early enough that everything is still easy to set up, late enough that you know what your actual paycheck and rent look like. Nothing here takes more than an afternoon in total, and doing it now means the first payment is a calendar event rather than a surprise.
If you want the wider view of that first year rather than just the next sixty days, the post-grad repayment playbook covers it end to end.
Here is the checklist, laid out by week.
Week-by-week checklist
Weeks 8–7 out: confirm what you owe and to whom.
Log in at studentaid.gov with your FSA ID and pull your loan summary. You are looking for four things on each loan: the balance, the interest rate, the loan type, and the servicer. For private loans, your credit report at annualcreditreport.com lists the balance and servicer.
Write them down in one place. This list is the foundation for every decision that follows, and it is the same information any lender or comparison tool will ask you for later.
Weeks 6–5: verify your contact information with every servicer.
Create an online account with each servicer if you have not already. Then check the email address and mailing address on file — for a lot of new grads, the address is still a campus mailbox or a parent’s house, and the email is a school account that may be shut off.
This is the single most common reason a first bill goes unseen. It takes five minutes per servicer to fix.
Weeks 4–3: pick your repayment plan and set up autopay.
Your servicer assigned you a default plan, usually Standard. You are not stuck with it — federal borrowers can change plans at any time at no cost. If the Standard payment fits your budget, it clears the debt fastest and costs the least in total interest. If it does not, income-driven repayment ties the payment to your income instead.
Then enroll in autopay. More on why below.
Weeks 2–1: run the payment through your actual budget.
Not a projected budget — the real one, with the rent you actually pay. Move the payment amount into a separate account or set the transfer up now, so the first month is a test run rather than a live fire.
If the number does not fit, this is the moment to change plans, not the month after a missed payment.
Has interest been accruing this whole time?
For a lot of loans, yes — and this is the detail that catches people off guard.
The grace period pauses your payments. It does not necessarily pause interest.
Subsidized vs. unsubsidized
On Direct Subsidized loans, the federal government generally covers the interest during the grace period. The balance you graduated with is roughly the balance you start repaying.
On Direct Unsubsidized loans, interest generally accrues from the day the loan was disbursed, including during school and during the grace period. That accrued interest may be added to your principal when repayment begins, which means you start paying interest on a slightly larger balance.
Private loans set their own terms, and they vary. Your loan agreement is the authority.
None of this is a reason to panic. It is a reason to look at your current balance rather than the number you remember from your financial aid letter, because they may not be the same. And if you have cash available, making a payment toward accrued interest before repayment starts can keep it from being added to your principal.
One qualifier worth knowing: Parent PLUS loans do not follow the same six-month grace period pattern as Direct Subsidized and Unsubsidized loans. If a parent borrowed on your behalf, that loan needs to be checked to confirm its terms.
Set up autopay before the first bill
If you do one thing on this list, do this one.
Autopay removes the possibility of forgetting a payment. Payment history is the largest single factor in your credit score — the same score that will determine what any future lender offers you, including if you decide to refinance later. Protecting it from the very first payment is worth more than most people realize at the time.
The 0.25% discount
There is a second reason. Many lenders and servicers offer an interest rate reduction — often around 0.25% — simply for enrolling in automatic payments.
It is a small number that runs for the entire life of the loan, and it costs you nothing but a few minutes of setup. There are not many pieces of financial advice that are this cheap and this durable.
One practical note: make sure the account you link keeps enough of a cushion to cover the payment. An autopay attempt against insufficient funds creates a different set of problems than the one it solved.
Refinance now, or after the first payment?
If you are weighing it seriously, Admire’s refinancing overview lays out how the marketplace works.
This question comes up constantly at the sixty-day mark, so here is the honest version.
The case for waiting. Most refinancing lenders want to see employment history, and a few months of on-time payments strengthens your credit file. Refinancing1 during your grace period usually means applying with the thinnest version of your profile — which tends to mean being priced accordingly. Around ninety days into repayment is generally a more productive time to look.
The case for looking now anyway. Comparing rates with a soft credit check costs nothing and does not affect your score. Even if you decide to wait, you learn where you currently stand and what would need to change. That is useful information to have before the first payment, not after.
The case that applies to almost everyone with federal loans: understand what you would be giving up first. Refinancing federal loans with a private lender converts them to private debt permanently. Income-driven repayment, federal deferment and forbearance options, and forgiveness programs including Public Service Loan Forgiveness all end at that point. If you work in public service, or your income is variable, that trade-off deserves real thought rather than a quick decision during a busy month.
The full trade-off is laid out in our complete guide to refinancing, and if you want to understand how lenders will actually price you before you compare anything, how lenders price refinancing breaks down the five inputs they weigh.
Want to know where you stand before the first bill?
Comparing offers on Admire takes about two minutes and uses a soft credit check, so it will not affect your score. You will see real numbers from multiple lenders side by side — and if the answer is “wait a few months,” that is genuinely useful to know now rather than later.
What happens if you miss it
Worth knowing, even if you have no intention of being here.
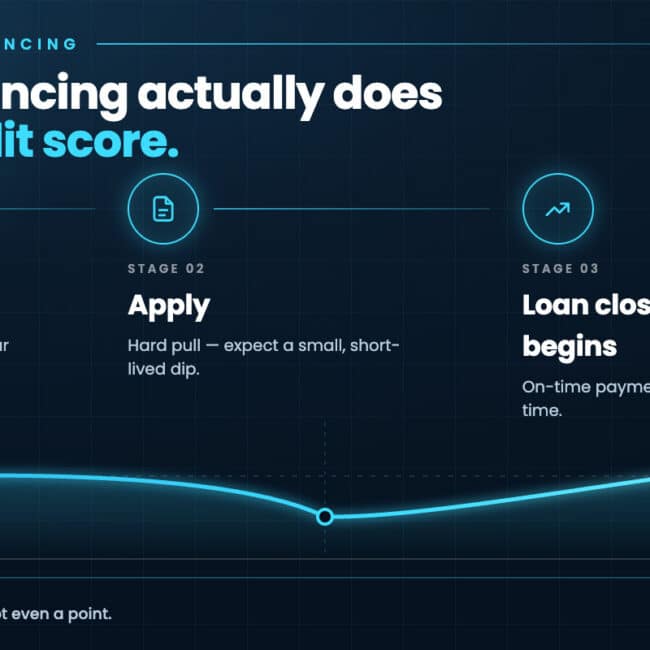
A federal loan is considered delinquent the day after a missed payment. Delinquency is typically reported to the credit bureaus once a payment is 90 days late, and that report affects your credit score.
The important part is that there are options well before it gets there, and they are free. Deferment and forbearance can pause payments temporarily. Switching to an income-driven plan can lower the payment to something manageable — in some cases substantially. Your servicer can walk you through both, and calling them early is the entire difference between a temporary adjustment and a lasting mark on your credit.
If you are already past a due date, the path back is straightforward: contact your servicer, ask what options apply to your situation, and get current. This is a routine conversation for them.
Frequently asked questions
When exactly does my grace period end?
Direct Subsidized and Unsubsidized loans typically have a six-month grace period that starts when you graduate, leave school, or drop below half-time enrollment. Your exact date is listed in your account at studentaid.gov. Parent PLUS loans follow different terms, and private loans are set by the individual lender.
Does interest build up during the grace period?
On Direct Unsubsidized loans, interest generally accrues during the grace period and may be added to your principal when repayment begins. On Direct Subsidized loans, the government generally covers it. Private loan terms vary by lender, so check your loan agreement.
Can I start making payments before the grace period ends?
Yes, and there is no penalty for doing so. Early payments go toward accrued interest first, which can keep that interest from being added to your principal when repayment starts.
Can I change my repayment plan after I have started?
Yes. Federal borrowers can change plans at any time at no cost, with no limit on how often. Processing takes a few weeks, so submit the change ahead of the payment you want it to affect.
Should I refinance before my first payment is due?
Usually there is no rush. Most lenders want to see employment history, and your credit profile tends to be stronger after a few months of on-time payments. Comparing rates with a soft credit check costs nothing in the meantime — and if any of your loans are federal, weigh the permanent loss of federal protections before refinancing at any point.
1Admire is not a lender and does not make credit decisions. All rates and terms are determined by participating lenders and depend on your individual financial situation. Not all consumers will qualify for advertised rates and terms. See our full disclaimers.